


Free written scope consultation - allowances, timeline, and change-order rules on paper before a single trade is scheduled
Styles & brands we work with
- Kitchen remodeling
- Bathroom remodeling
- Home additions & ADU
- Roofing
- Windows & doors
- Driveway & pavers
- Fence
See the difference
 Before
 After
 Before
 After
 Before
 After
Do Impact Windows Lower Insurance in North Miami Beach? Yes – If You Document Them
Yes, impact windows lower homeowners insurance in Florida, but the credit only lands if a licensed inspector sees the Miami-Dade NOA number for each installed unit on your OIR-B1-1802 wind mitigation form. A contractor receipt alone doesn’t do it. Installing impact windows and never updating that report is like buying a discount card and never scanning it. Homeowners who skip the documentation step routinely leave $500-$2,000 a year in credits unclaimed. Call (844) 797-4868 and we’ll walk you through the paperwork path before the first pane goes in.

Why the Wind Mitigation Report Is the Whole Game
Florida insurers don’t discount your premium because your windows look tough. They discount it because a licensed inspector certifies, on the OIR-B1-1802 form, that your opening protection meets the standard. That form asks for the Miami-Dade Notice of Acceptance number on every window and door, not the name of the company that installed them.
Where the paperwork falls apart is right there. A homeowner pulls the trigger on eight ES Windows units across the front of a 1962 concrete-block ranch west of Biscayne Boulevard, feels the difference during the next squall, then finds out at renewal that the discount was never applied. The inspector showed up, couldn’t match a NOA to half the openings, and marked the section partial. Partial credit on the biggest line item of the form is money left on the table every single year.
We hand over complete NOA documentation for every window and door unit we install, formatted so you can attach it directly to your wind mitigation inspection request. No digging through email folders two years later. That’s the gap we close.
How the Opening Protection Credit Actually Stacks Up in North Miami Beach
The OIR-B1-1802 form scores several features, and “opening protection” carries the largest single discount of the group. But it only maxes out when all openings are impact-rated. That includes the garage door and any skylights. A partial replacement – say, the front windows and slider but not the garage – often lands in a middle tier and leaves real money behind.
Here’s the second layer most people miss. Citizens Insurance, which covers a meaningful share of North Miami Beach homeowners, uses the same wind mitigation report to set your named-storm deductible. Fully documented impact openings can move that deductible from 5% to 2% of dwelling value. On a $500,000 home, that’s $15,000 less exposure every named storm. Not a discount on the premium – a change to how much you owe before coverage kicks in.
And because North Miami Beach sits inside Miami-Dade’s High Velocity Hurricane Zone, insurers start from a higher baseline premium here than they do inland. A given percentage discount on a bigger base produces a bigger dollar check. The same impact windows that save a few hundred dollars a year in Orlando or Tampa can save considerably more along the U.S. 1 corridor.
What the Credit Typically Looks Like
| Line on your report | What it covers | Relative value |
|---|---|---|
| Opening protection | Impact-rated windows, doors, garage door, skylights | Largest single discount on the form |
| Roof covering | Roof material and age | Moderate |
| Roof deck attachment | How the deck is fastened | Moderate |
| Secondary water barrier | Underlayment protection | Smaller |
Impact window installation in North Miami Beach runs $9,440-$29,500 depending on unit count, frame material, and whether we’re matching existing stucco openings on a mid-century home. Standard window replacement without impact rating lands at $5,310-$17,700. The delta up front is real. So is the annual credit and the deductible shift, which is why we run the math with homeowners before ordering anything.
Common Local Scenarios Where the Credit Gets Missed
Most of what we see isn’t exotic. It’s ordinary North Miami Beach housing stock running into an ordinary documentation gap.
- The 1960s block ranch with a stubborn garage door. Windows and sliders get replaced, the garage door doesn’t, and the opening protection credit caps out in a middle tier. We flag this before the order, because replacing the garage door later means a second inspection.
- The condo owner who upgraded the unit but not the report. Mid-rise units along U.S. 1 often have association-level opening protection that never got documented per-unit. We help owners collect the right NOA paperwork for their individual windows and doors.
- The homeowner who used a handyman and a big-box order. No NOA trail, no inspector match, no credit. It happens often enough that we now ask every caller whether they have their previous documentation before we quote.
- The renewal surprise. A policy renews, the premium jumps, and the homeowner assumes the windows “didn’t work.” Usually the credit was never filed, or the inspector noted deteriorated seals that undercut the rating.
That last one is where the 730-Day Done Right Promise earns its keep. If it isn’t done right, we make it right. The wind mitigation inspector is going to look at frame seals, anchor security, and hardware function. Our promise covers the installation integrity that inspector evaluates, so the credit documented at install stays supportable at renewal. Built to last, backed in writing.
Getting the Documentation Right From Day One
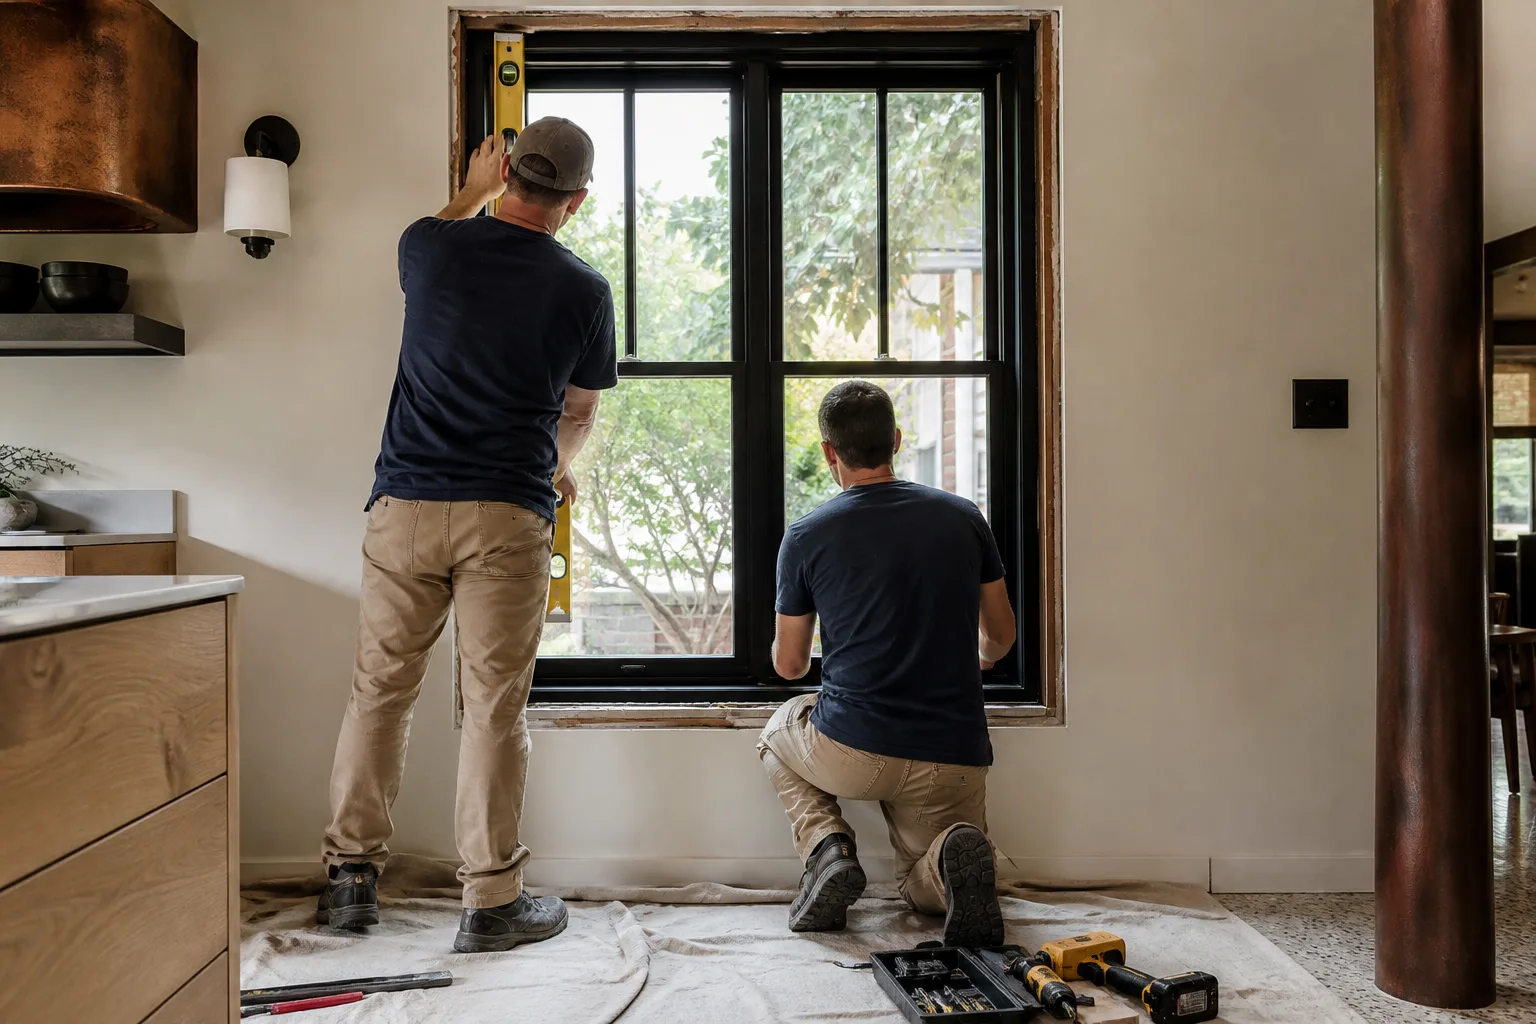
The cleanest path is to plan the paperwork before the install. We match each opening to a product with a valid Miami-Dade NOA – brands like ES Windows, ECO Window Systems, and Therma-Tru doors all carry the documentation trail inspectors want. Then we assemble the NOA packet per unit and hand it to you with the final walkthrough.
Our technicians have up to 12 years of experience with South Florida opening protection, and we know the inspection quirks that come with mid-century stucco homes just above the water table. Condensation, stucco matching, and anchor depth all come up. None of it changes the credit calculation, but all of it affects whether the inspector marks the openings as compliant.
If you want a full picture of what we install, the Windows & Doors page covers product lines and process. For a broader look at how we handle the whole home, start at our home page and the North Miami Beach service area pages.
FAQs
Yes – impact windows typically reduce homeowners insurance premiums in North Miami Beach and can also lower your named-storm deductible from 5% to 2% of dwelling value when fully documented. The discount depends on a licensed inspector completing the OIR-B1-1802 wind mitigation form and matching a Miami-Dade NOA number to each installed unit. Call (844) 797-4868 for a free estimate and we’ll explain what documentation we provide.
Most North Miami Beach homeowners we work with see $500-$2,000 in annual premium credits after a fully documented impact installation. The exact figure depends on your carrier, dwelling value, and whether all openings – including the garage door – are impact-rated. Partial replacements land in a middle tier and save less. Call us for a free estimate and we’ll review your specific openings.
Citizens uses the same OIR-B1-1802 report but applies it to your named-storm deductible as well as your premium, so the deductible shift from 5% to 2% is often the bigger number. On a $500,000 home, that’s $15,000 less exposure per named storm. Document all openings and the credit applies. Call (844) 797-4868 to walk through your coverage.
Partially – a partial replacement can earn a reduced opening protection credit, but the maximum discount requires every opening to be impact-rated, including the garage door and any skylights. We often recommend phasing the project so the final phase completes all openings and triggers the top tier. Upfront pricing plus 0% financing for 18 months makes that phase plan workable. Estimates are free.
Your carrier will apply a lower credit tier or deny the opening protection credit entirely, which is exactly the $500-$2,000 annual gap most homeowners never see. We provide NOA documentation for every unit we install, formatted for direct submission with your wind mitigation inspection request. Call (844) 797-4868 and we’ll confirm what your carrier needs.
Ready to Close the Documentation Gap?
If you’d rather have it looked at, Groundwork Construction Co. of North Miami Beach offers a no-pressure assessment in North Miami Beach – call (844) 797-4868 for a free estimate. We’re a live person, 24/7, no voicemail. Upfront pricing, no surprises, and every project backed by the 730-Day Done Right Promise. Financing at 0% for 18 months and $1,000 off projects over $10,000 are available.
Written by the team at Groundwork Construction Co. of North Miami Beach, serving North Miami Beach, FL.


